
A gym equipment donation appraisal is the step that is easiest to skip when a retired strength line goes to a high school, and it is the step that decides whether the deduction survives a review. The equipment moves, the receiving school sends a thank-you letter, and the write-off goes on the return at the number someone remembered from the original invoice. That sequence fails on two separate rules at once.
- Where a gym equipment donation appraisal becomes mandatory
- The deduction is often less than fair market value
- Fair market value is not replacement cost
- Six checks before the equipment leaves the building
- A worked example with stated assumptions
- What a gym equipment donation appraisal has to contain
- Warning signs and common mistakes
- Does a donated treadmill need its own appraisal?
- Who pays for the appraisal?
- What to do before the next floor refresh
Year-end is when it happens. Floors get refreshed before January, removal crews are already booked, and a nonprofit that will take the old units for free is cheaper than paying for disposal. The tax treatment is a real benefit, but it is a benefit with documentation attached. A gym equipment donation appraisal is the piece of that documentation with the tightest deadline, and it has to exist before the return is filed.
Where a gym equipment donation appraisal becomes mandatory
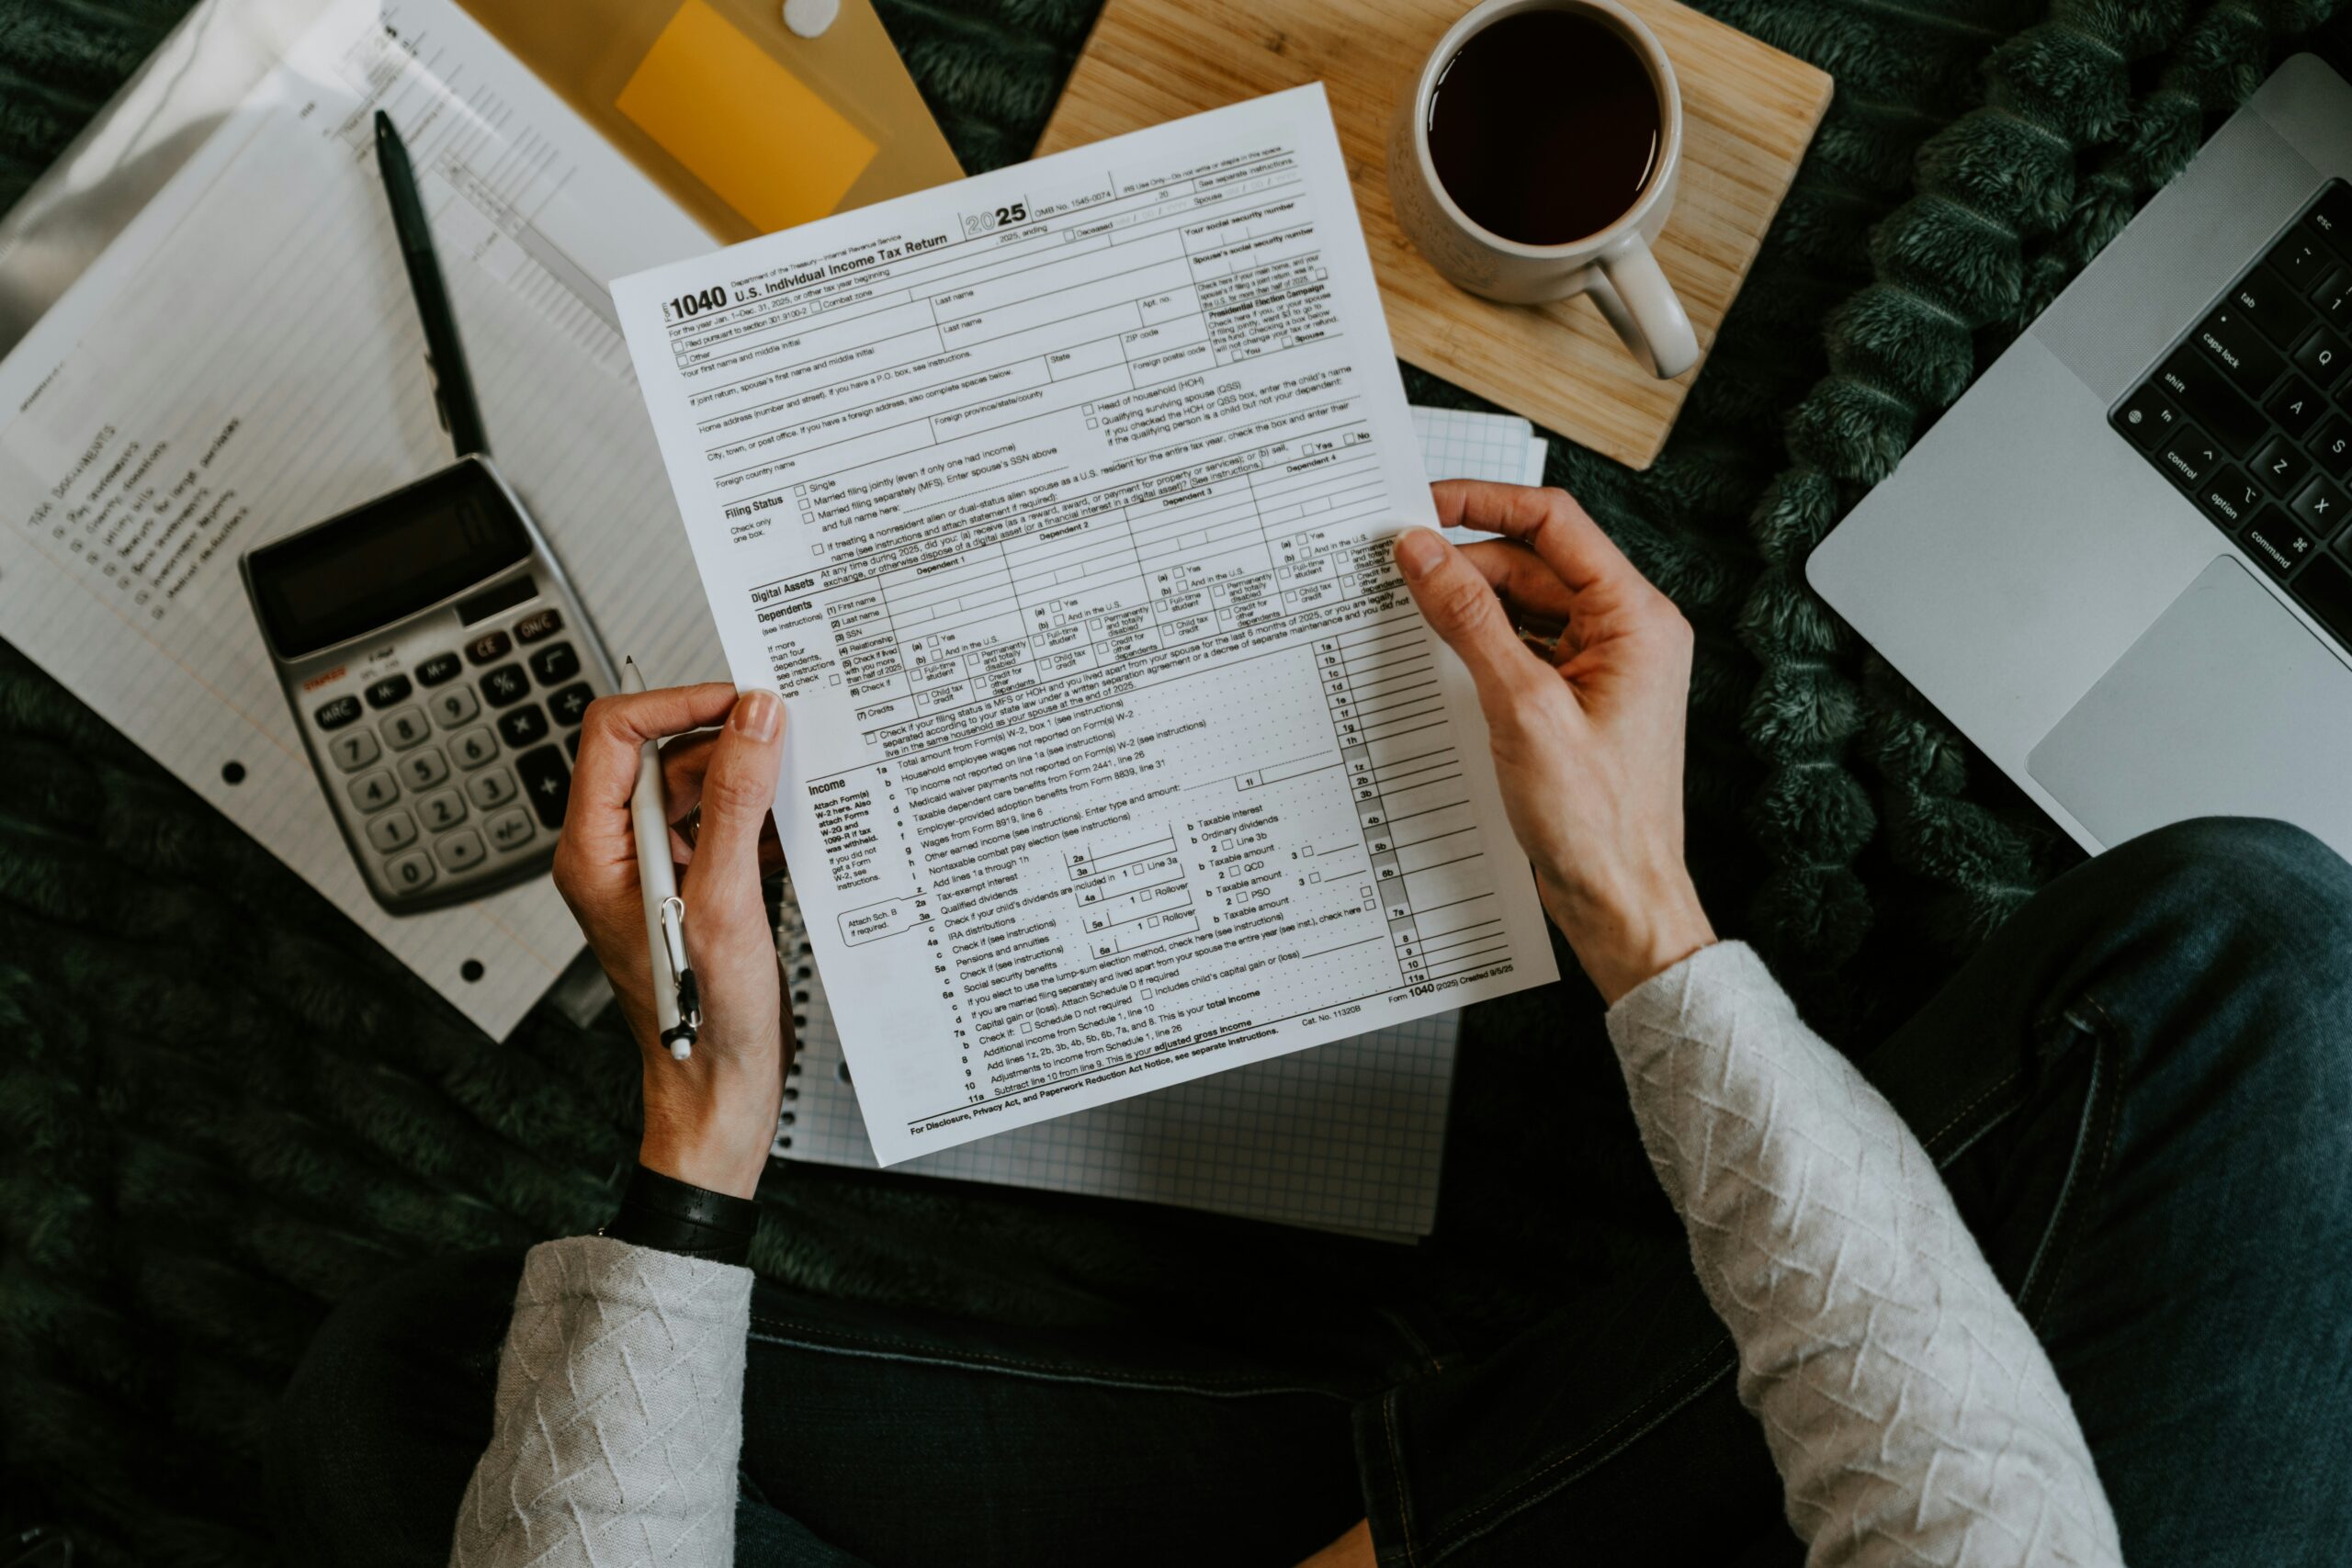
The threshold is per item, not per donation. The IRS instructions for Form 8283, revised December 2025, direct filers to “use Section A to report donations of property for which you claimed a deduction of $5,000 or less per item” and to “use Section B to report donations of property for which you claimed a deduction of more than $5,000 per item.” A noncash contribution of more than 500 dollars but not more than 5,000 dollars requires Section A to be fully completed.
Section B is where the appraisal obligation lives. The instructions state that “items reportable in Section B require a written qualified appraisal by a qualified appraiser,” and that “a separate, qualified appraisal is required for any gift of property valued in excess of $5,000.” The appraisal has to be in hand first: “you must get a written qualified appraisal from a qualified appraiser before completing Part I.”
For a gym floor, that line falls in an awkward place. A single commercial treadmill or a selectorized machine will often land under the per-item threshold, while a full rack system or a cable jungle can clear it on one unit. Similar items must be weighed together: the instructions direct a filer to “consider all items in the group,” “even if items in the group were donated to more than one donee organization.” That grouping question is worth putting to the donor’s own tax adviser before the units are loaded.
The deduction is often less than fair market value
This is the rule that surprises people who did the appraisal correctly. Publication 526 for 2025 explains that property is ordinary income property if the donor “would have recognized ordinary income or short-term capital gain” on a sale at fair market value, and that “the amount you can deduct for a contribution of ordinary income property is its FMV minus the amount” that would be ordinary income on such a sale. The publication adds plainly: “Generally, this rule limits the deduction to your basis in the property.”
Depreciated equipment is squarely in that category. Publication 526 states that “property used in a trade or business is considered ordinary income property to the extent of any gain” that would have been treated as ordinary income because of depreciation. Equipment that has been written down through accelerated depreciation or a Section 179 election can therefore carry a low adjusted basis even while it still has real resale value.
The practical effect is a two-number problem. An appraisal might support an assumed fair market value of 46,000 dollars for a retired strength line, while the deduction is generally capped near the adjusted basis, which may be a small fraction of that. The appraisal is still required to support the Section B filing, but it does not by itself set the deductible amount.
A further limit reached contributions made in 2026: IRS Publication 505 for 2026 states that beginning in 2026, “if you itemize, you can only deduct charitable contributions that are more than 0.5% of your adjusted gross income,” and that any amount under that floor “can’t be deducted in 2026.” How that floor, depreciation recapture and any separate limit on a corporate donor combine is a question for the donor’s accountant rather than the dealer.
Fair market value is not replacement cost
Publication 561, also revised December 2025, defines fair market value as “the price that property would sell for on the open market,” agreed between “a willing buyer and a willing seller, with neither being required to act, and both having reasonable knowledge of the relevant facts.” It lists the factors that are relevant to that determination: cost or selling price, sales of comparable properties, replacement cost, and the opinions of professional appraisers.
The publication is direct that replacement cost is not a shortcut. It states that “in most cases, there is no relationship between the replacement cost and the FMV,” and warns that replacement cost new less observed depreciation, used alone, “usually does not result in a determination of FMV” and “generally tends to set the upper limit of value, particularly in periods of rising costs.” It also notes that a cost or selling price carries less weight when the purchase or sale was not reasonably close in time to the contribution.
That is why an insurance schedule is the wrong document to hand an appraiser. Replacement value on a property policy answers a different question, and the comparable market for used commercial equipment is the auction and resale market, not the new-equipment price list. Anyone who has priced auction lots and an all-in bid ceiling already knows how far apart those two numbers can sit.
Six checks before the equipment leaves the building
- Fix the per-item values first. Build a line-item schedule with make, model, serial number and condition before anything is loaded, and decide from it which items will be claimed above 5,000 dollars. The schedule, not the truck manifest, determines whether Section B applies.
- Engage the appraiser inside the 60-day window. The Form 8283 instructions require that “the appraisal must be signed and dated by a qualified appraiser not earlier than 60 days before the date you contribute the property,” and that the donor receive it before the return’s due date including extensions.
- Check the appraiser against the qualification tests. The instructions require that the individual “regularly prepares appraisals for which they are paid,” that the appraisal carry a declaration of qualification “because of their experience and education,” and that the appraiser specify “the appraiser’s education and experience in appraising the type of property.” The appraiser must also complete Part IV of the form.
- Keep the dealer out of the appraisal. Generally “a party to the transaction in which you acquired the property being appraised will not qualify to sign the declaration.” A dealer that sold the equipment to the club, or that is handling the removal, should not be the one valuing it.
- Get the donee acknowledgment signed. The donee organization “must complete and sign the Donee Acknowledgment in Part V,” by an official authorized to sign the organization’s tax returns or a person specifically designated. A gift receipt on letterhead is not that signature.
- Confirm the deduction amount with the donor’s adviser. Because the ordinary income property rule generally limits the deduction to basis, the appraised value and the claimed value can legitimately differ. That reconciliation belongs in the file before the return is prepared.
A worked example with stated assumptions
The figures below are assumptions chosen to show how the two rules interact. They are not survey data and not a valuation of any real equipment.
| Item | Assumed original cost | Assumed adjusted basis | Assumed appraised FMV | Section B needed |
|---|---|---|---|---|
| Selectorized circuit, 12 stations | 74,000 dollars | 0 dollars | 21,000 dollars | Yes, group of similar items over 5,000 dollars |
| Half-rack, one unit | 4,900 dollars | 0 dollars | 1,750 dollars | No, under the per-item threshold |
| Cardio bank, 8 treadmills | 61,600 dollars | 9,000 dollars | 14,400 dollars | Yes, group of similar items over 5,000 dollars |
| Totals | 140,500 dollars | 9,000 dollars | 37,150 dollars | Sum of the rows above |
Read the last two columns together. The appraisal in this example supports 37,150 dollars of fair market value, while the ordinary income property rule would generally hold the deduction near the 9,000 dollar basis figure, because the fully depreciated items carry no basis at all. The appraisal is not wasted: without it the Section B items have no support, and the instructions warn that “your deduction generally will be disallowed if you fail to” attach and fully complete the form or obtain a required appraisal, subject to a reasonable cause exception.
What a gym equipment donation appraisal has to contain
Treat the report as evidence, not a formality. It should identify each item by make, model and serial number, state the condition and remaining service life the appraiser observed, name the market the value was drawn from, and show the comparable sales or other data behind the conclusion. It must carry the appraiser’s declaration, education and experience, and a signature date inside the 60-day window.
Two attachments make it durable. The first is photographic evidence of condition on the removal date, because the appraisal describes equipment that will no longer exist in that state by the time any review happens. The second is the removal and freight documentation that proves the date of the contribution, which is the date the 60-day rule runs against.
Condition is the part dealers can help with honestly. A technician’s inspection note on wear points, frame integrity, upholstery, console function and parts availability gives the appraiser something to work from, and it maps closely to the same evidence used to plan equipment retirement with an asset destination register. Supplying facts about condition is different from supplying a value.
Warning signs and common mistakes
The clearest warning sign is a value that traces back to an invoice. Original cost is a historical fact about a purchase, not evidence of what the equipment would sell for now, and Publication 561 treats a purchase price as carrying less weight when the property was not bought or sold at a time that is reasonably close to the date of contribution. A deduction built on the purchase price is the easiest kind to unwind, and a gym equipment donation appraisal exists precisely to replace that number with market evidence.
Four mistakes recur. Donating first and appraising later breaks the 60-day rule, and an appraisal dated after the contribution cannot be cured by backdating. Using the removal contractor or the selling dealer as the appraiser risks the declaration itself.
Accepting a thank-you letter in place of a signed Part V leaves the Section B filing incomplete. Claiming appraised value without checking basis overstates the deduction even when the appraisal is sound.
There is also a decision that comes before any of this. Donation is one disposition route among several, and it is not automatically the best one. Equipment with a real second life may be worth more through trade-in and resale after removal and freight costs than it is worth as a basis-limited deduction, and that comparison should be run before the units are promised to anyone.
Does a donated treadmill need its own appraisal?
Generally only if the deduction claimed for that unit is more than 5,000 dollars, which a single treadmill often will not reach. Similar items may need to be considered together, and that grouping question, along with the per-item determination, is one for the donor’s tax adviser rather than the dealer or the receiving charity.
Who pays for the appraisal?
The donor needs it, so the donor normally arranges and pays for it, and the appraiser must be independent of the transaction. A dealer can reasonably help by producing the equipment schedule, serial numbers and a technician’s condition report, and by documenting the removal date. That support strengthens the file without putting the dealer in a role the instructions exclude.
What to do before the next floor refresh
Build the line-item schedule while the equipment is still installed, book the appraiser before the removal date rather than after it, and ask the donor’s accountant for the basis figures on the units in question. Compare the basis-limited deduction against a trade-in or auction outcome before committing the equipment. Then keep one file per donation holding the schedule, the appraisal, the signed Part V acknowledgment, the condition photographs and the removal paperwork, and remember that the depreciation side of the same equipment runs on when depreciation starts on equipment placed in service.